Invoicing as a self-employed healthcare professional in the Netherlands: VAT-exempt or 21%?
12 November 2026 · 6 min read · checked and edited by Jarno van den Hove
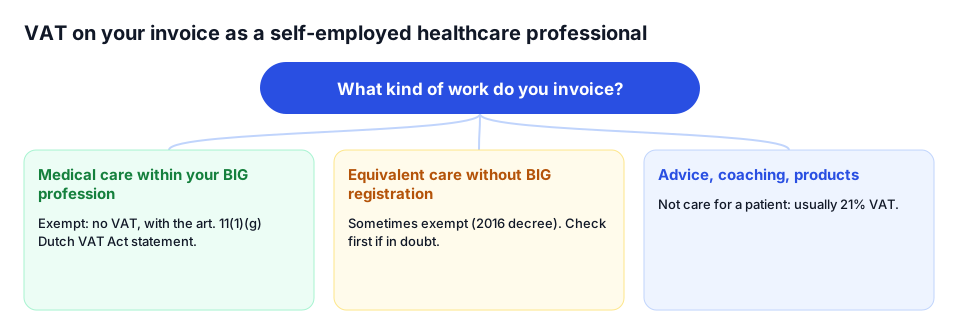
If you work as a self-employed healthcare professional in the Netherlands, your work is often exempt from VAT: no VAT goes on your invoice. The medical exemption covers healthcare given by someone in a profession regulated by the Wet BIG (the Dutch Individual Healthcare Professions Act), within that profession’s field of expertise. Work that is not medical care, such as advice or coaching, usually carries the standard 21% VAT. (General information, not tax advice.)
What the law says
The exemption is in Article 11(1)(g)(1°) of the Dutch VAT Act (Wet op de omzetbelasting 1968), based on Article 132(1)(c) of the EU VAT Directive. A 2016 decree of the State Secretary explains how the Belastingdienst applies it. In short, the exemption applies when:
- You practise a profession regulated by the Wet BIG and completed the training for it
- You are registered in the BIG register, where the Wet BIG requires it
- The service is healthcare for people, with a therapeutic purpose
- The work falls within the field of expertise of your profession
Freelance nurses and hospital work
For years the position was that a freelance nurse working in a hospital under the direction of others had to charge VAT. The Dutch Supreme Court (Hoge Raad) ruled otherwise on 13 June 2014: that work is exempt too, which the State Secretary confirmed in a letter to Parliament on 9 July 2014. A medical staffing agency that hires out healthcare staff does not fall under the exemption; that is the agency’s own service. If you work through an agency or platform, check who provides the care and who invoices you.
When do you charge VAT?
Not BIG-registered? In some cases you can still apply the exemption, if your care is of equivalent quality to that of a BIG profession; the 2016 decree sets out the conditions. If in doubt, check with the Belastingdienst or an adviser before you invoice without VAT.
- Services without a therapeutic purpose, such as purely cosmetic treatments
- Work outside your field of expertise, even if you are BIG-registered
- Coaching, advice or writing protocols for an organisation: that is not care for a patient
- Training and workshops, unless a separate education exemption applies
- Selling products, such as aids or supplements
What goes on a VAT-exempt invoice
- All the usual details: your name and address, KVK number, invoice number, date, description of the care, period and amount
- No VAT amount and no VAT rate
- Why there is no VAT, for example: “Exempt from VAT under Article 11(1)(g) of the Dutch VAT Act 1968 (medical care)”
- Your BIG number: not mandatory, but many clients ask for it
Worked example: care plus advisory work
In November 2026 you work as a freelance nurse directly for a care institution: 96 hours × €52.00 = €4,992.00. You also write a working protocol for the institution for €400.00. The care is invoiced without VAT, €4,992.00, with the exemption statement. The protocol is not care: €400.00 + 21% VAT = €484.00. One invoice with the right VAT per line is allowed, but in Factando you make two invoices: one exempt, one at 21%. Together €5,476.00, of which €84.00 VAT. Only the €400.00 turnover and €84.00 VAT go into your VAT return (box 1a).
VAT return and VAT on your costs
You do not pay VAT on exempt turnover. The flip side: you cannot deduct the VAT on costs you make for that exempt work. If you do both exempt and taxable work, you deduct only the VAT that belongs to the taxable part. The small business scheme (KOR) is not needed for exempt care, since you charge no VAT on it anyway.
Healthcare invoices in Factando
In Factando, choose “VAT-exempt: medical care” as the VAT treatment. Your invoice then shows no VAT and carries the statement “Exempt from VAT under Article 11(1)(g) of the Dutch VAT Act 1968 (medical care)”, in Dutch, English, German or French depending on your client’s language. The e-invoice (UBL/Peppol) gets the matching exemption code. A VAT ID is not required for such an invoice. In your VAT overview this turnover is listed separately, outside the return, with a reminder about VAT on your costs. Doing taxable work as well, such as advice? Make a separate invoice with 21% VAT for that.
Sources
The rules in this article come from these official pages. Check the current amounts and deadlines there.
Frequently asked questions
Do I charge VAT as a self-employed healthcare professional in the Netherlands?
For medical care within your BIG profession usually not: it is exempt. For non-medical services, such as advice or coaching, you usually charge 21% VAT.
What do I put on my invoice if I am exempt?
All the usual invoice details, no VAT amount, and a statement such as “Exempt from VAT under Article 11(1)(g) of the Dutch VAT Act 1968 (medical care)”.
Am I exempt if I work in a hospital?
As a freelancer in a BIG profession who provides the care yourself: yes, also in a hospital. That follows from a Dutch Supreme Court ruling of 13 June 2014. An agency that hires out staff is not exempt.
Can I deduct VAT on my costs?
Not on costs that belong to your exempt care. If you also do taxable work, you deduct only the VAT that belongs to that taxable work.
Done with invoicing by hand?
Factando makes a correct Dutch invoice for you: numbering, VAT and layout are handled automatically. Try it free without an account; saving and sending takes a free account (3 sent invoices a month). Pro, with automatic payment reminders, is free for 14 days.